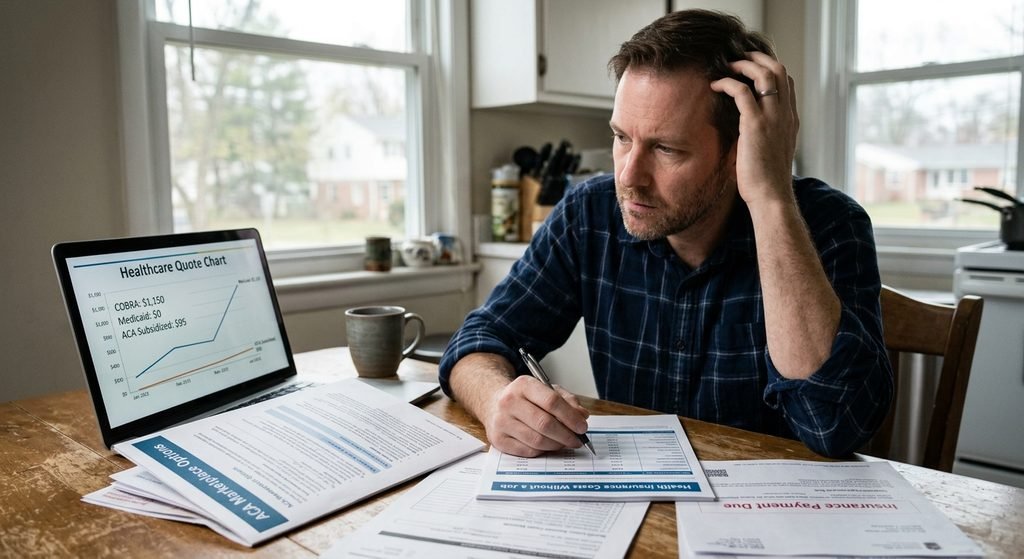
Losing a job is stressful enough on its own, but in the United States, it almost always comes with a terrifying second thought: “What happens to my health insurance, and how much is this going to cost me out of pocket?”
Over my last 9 years working as an independent health insurance advisor and helping hundreds of individuals navigate job transitions, layoffs, and career breaks, I’ve answered this exact question more times than I can count.
The honest answer? It depends entirely on the path you take.
Without a job, health insurance in the US can cost anywhere from $0 per month (via Medicaid or heavy ACA subsidies) to well over $700–$1,500+ per month if you opt for full-price COBRA or unsubsidized private coverage.
In this comprehensive guide, I’m breaking down every single option, the real hidden costs, and how you can protect your wallet and health when you don’t have an employer paying part of your premium.
The Reality of Job-Based Health Coverage (And What Happens When It Ends)
When you are employed full-time, your employer typically covers 70% to 80% of your monthly health insurance premium. You only see your small portion deducted from your bi-weekly paycheck, so it’s easy to forget what healthcare actually costs in America.
The minute you resign or get laid off, that employer subsidy disappears. You are suddenly exposed to the full retail price of health coverage.
However, being unemployed opens up a Special Enrollment Period (SEP) under US federal law. This means you do NOT have to wait for the standard end-of-year Open Enrollment period to sign up for a new plan. You generally have 60 days from the date you lost your coverage to select a new option.
4 Main Options for Health Insurance When Unemployed (With Real Costs)
Let’s look at the four main routes you can take, ordered from most expensive to most affordable.
+-------------------------------------------------------------------------+
|                  HEALTH INSURANCE OPTIONS WHEN UNEMPLOYED               |
+--------------------------+-----------------------+----------------------+
| Option                   | Avg Monthly Cost      | Best Used For        |
+--------------------------+-----------------------+----------------------+
| 1. COBRA Continuation    | $600 - $1,500+ / mo   | Short gaps, high care|
| 2. ACA Marketplace       | $0 - $450 / mo (sub)  | Long-term, budget    |
| 3. Medicaid              | $0 / mo               | Low / No income      |
| 4. Short-Term Insurance  | $150 - $350 / mo      | Very short, healthy  |
+--------------------------+-----------------------+----------------------+
Option 1: COBRA Continuation Coverage (The Most Expensive Route)
What Is COBRA?
The Consolidated Omnibus Budget Reconciliation Act (COBRA) allows you to stay on the exact same health insurance plan you had with your former employer for 18 to 36 months.
Real Monthly Cost:
- Individual: $600 – $800 per month
- Family: $1,800 – $2,200+ per month
- Administrative Fee: Up to a 2% fee added by your former employer.
My Advisor Insight on COBRA:
In my 9 years of consulting, I usually advise clients to avoid COBRA unless they meet very specific conditions. Why? Because you are paying 100% of the plan cost plus an admin fee.
When to choose COBRA:
- You have already hit your out-of-pocket maximum or annual deductible for the current year on your employer plan.
- You are undergoing active medical treatment (like chemotherapy or surgery) and cannot risk changing doctors mid-treatment.
Option 2: ACA (Obamacare) Marketplace Plans (Best Overall Value)
How It Works:
You shop through Healthcare.gov (or your state’s marketplace). Marketplace plans are categorized by metal tiers: Bronze, Silver, Gold, and Platinum.
Real Monthly Cost:
- Unsubsidized Average: Around $450 – $680/month for a Silver tier plan.
- With Subsidies (Premium Tax Credits): $0 to $100/month for most unemployed individuals.
Why ACA Subsidies Matter When You Lose Your Job:
Subsidies are calculated based on your estimated annual income for the current calendar year, not your past salary.
If your income drops significantly due to job loss, your projected annual income decreases. This qualifies you for Advanced Premium Tax Credits (APTC) and Cost-Sharing Reductions (CSRs) on Silver plans, which drop your monthly premiums drastically.
Option 3: Medicaid (Zero or Low-Cost Safety Net)
How It Works:
Medicaid is a state and federally funded program for individuals and families with limited income.
Real Monthly Cost:
- $0 per month (or nominal copays like $1 – $3 for prescriptions).
Who Qualifies?
If you live in a state that expanded Medicaid under the ACA, you can qualify if your monthly income drops below 138% of the Federal Poverty Level (FPL).
Pro-Tip from Experience:
Unlike Marketplace plans that look at your annual income, Medicaid looks at your current monthly income. If you currently have zero income due to layoff, you may qualify for Medicaid immediately, giving you comprehensive coverage while you job hunt.
Option 4: Short-Term Health Insurance (Use With Extreme Caution)
How It Works:
Temporary health plans designed to bridge small gaps (e.g., 30 to 90 days) between jobs.
Real Monthly Cost:
- $150 to $350 per month.
The Catch (What Brokers Don’t Always Tell You):
Short-term plans are not ACA-compliant. They do not cover pre-existing conditions, maternity care, or mental health services, and they can deny your claim if you get sick. I only recommend these as a last-resort safety net for healthy individuals who just need catastrophic protection for a few weeks.
Key Factors That Determine Your Unemployed Health Insurance Cost
                   +----------------------------------+
                   |   FACTORS AFFECTING YOUR PREMIUM  |
                   +----------------------------------+
                                    |
     +-----------------+------------+------------+-----------------+
     |                 |                         |                 |
[ Your Age ]    [ Zip Code/State ]       [ Household Size ]  [ Projected Income ]
- Your Household Income Estimate: Lower projected annual income equals higher government subsidies.
- Where You Live: Health insurance premiums vary wildly by state. States like Maryland have lower average premiums, whereas Vermont or New York run much higher.
- Your Age: Under ACA rules, older adults (age 50–64) can be charged up to three times more than a 21-year-old for the exact same coverage.
Step-by-Step Decision Guide: What Should You Do Today?
If you recently lost your job or are planning to leave your workplace, follow this exact workflow I use with my own clients:
Step 1: Calculate your projected total income for the current calendar year.
   │
   ▼
Step 2: Check if your state expanded Medicaid.
   │   ├── Current monthly income = $0? ──► Apply for Medicaid ($0/mo).
   │   └── Current income above limit? ──► Move to Step 3.
   ▼
Step 3: Go to Healthcare.gov within 60 days of losing job coverage.
   │   ├── Qualify for Subsidies? ──► Enroll in a Silver ACA Plan ($10 - $150/mo).
   │   └── No Subsidies / High Income? ──► Compare ACA vs. COBRA.
   ▼
Step 4: Check COBRA Deductible Status.
       └── Already met full deductible this year? ──► Stick with COBRA for remaining months.
Benefits & Advantages of Switching to an ACA Plan Over COBRA
- Massive Monthly Savings: Subsidies lower premiums by hundreds of dollars.
- Essential Health Benefits Guaranteed: Pre-existing conditions, prescription drugs, mental health, and preventative care are 100% covered by law.
- No Job Dependency: Your policy stays with you regardless of whether you pick up freelance work, start a business, or remain unemployed.
Common Mistakes to Avoid When Buying Coverage Without a Job
- Missing the 60-Day Window: If you wait past 60 days from losing your job plan, you lose your Special Enrollment Period.
- Underestimating Annual Income: Be realistic with your income estimate on Healthcare.gov. If you land a high-paying job sooner than expected, you may have to reconcile and pay back part of your tax credit at tax time.
- Buying “Junk” Plans Online: Beware of sponsored ads selling non-regulated “indemnity” or “health share” plans that leave you stranded with huge hospital bills. Stick to Healthcare.gov or licensed state exchanges.
Final Thoughts: Finding Peace of Mind
Going without a job does not mean you have to go uninsured or go bankrupt paying for healthcare. Take a deep breath, run your numbers on the ACA Marketplace, check your Medicaid eligibility, and make an informed decision based on your health needs and budget.